
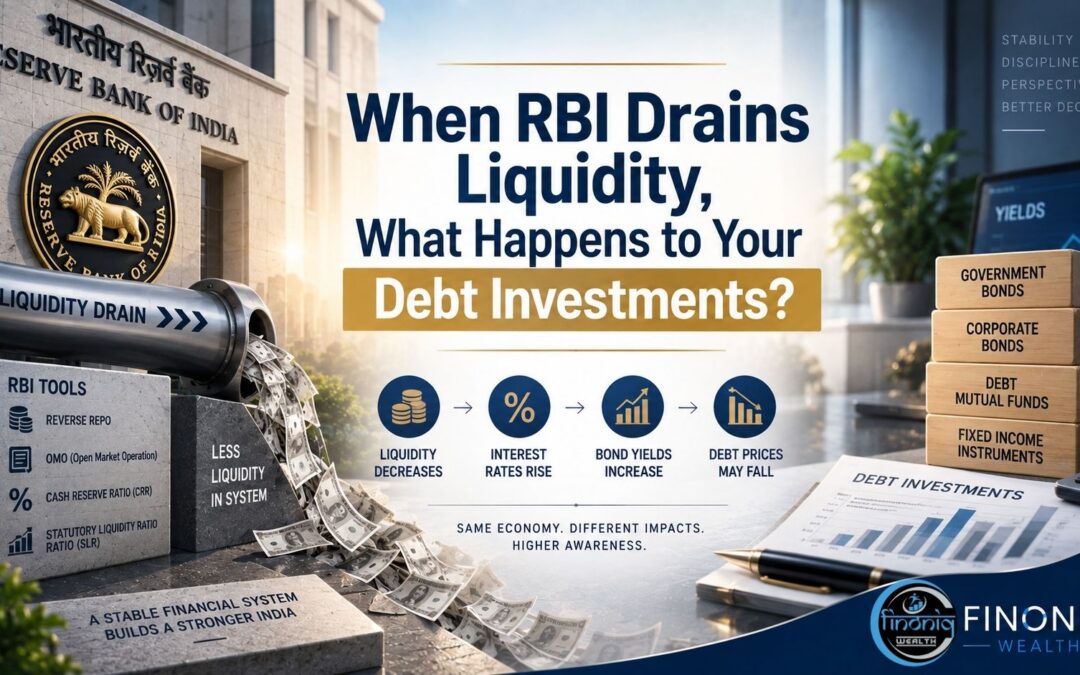
Imagine checking your debt investment one morning and noticing that its value has moved even though the underlying investment is supposed to be relatively stable.
You may wonder:
“Why did this happen? The company hasn’t defaulted. The government hasn’t changed the bond. So what changed?”
One possible answer lies much higher up in the financial system:
Liquidity.
When the Reserve Bank of India (RBI) adds money to the banking system, financial conditions can become easier. When it absorbs excess liquidity, conditions can become tighter.
And while this may sound like something that concerns only banks and economists, liquidity conditions can eventually influence the money market, bond yields, borrowing costs and the valuation of debt securities.
That brings us to an important investor-education question:
When RBI drains liquidity, what actually happens to your debt investments?
The answer is not as simple as saying “debt investments will fall.”
The impact depends on how liquidity is being drained, what happens to interest rates and yields, the maturity of the securities involved, and the type of debt investment being considered.
Introduction: What Does “Draining Liquidity” Actually Mean?
In simple terms, liquidity refers to the availability of money within the financial system.
The RBI manages system liquidity using several tools and operations. These include the Liquidity Adjustment Facility (LAF), variable-rate repo and reverse-repo operations, the Standing Deposit Facility (SDF), and open market operations (OMOs), among others. The RBI’s framework is designed to manage liquidity conditions and keep short-term money-market rates aligned with the monetary policy framework.
When the RBI absorbs liquidity, money is effectively moved out of circulation in the banking system for the relevant period.
Think of it like this:
More liquidity → easier availability of funds
Less liquidity → tighter availability of funds
But what does that have to do with bonds?
The connection becomes clearer when we understand the relationship between interest rates, bond yields and bond prices.
Why Does Liquidity Matter for Debt Investments?
Debt investments are not completely insulated from changes in financial-market conditions.
A bond has a price and a yield.
When market yields change, the market value of existing bonds can also change.
This is particularly important for securities with longer maturities.
The RBI itself explains that government securities are exposed to market risk: when interest rates move adversely, the market price of existing securities can fall, creating valuation losses for investors who sell or mark them to market.
So the chain can look like this:
RBI liquidity operation
↓
Money-market conditions change
↓
Interest-rate expectations and market yields can respond
↓
Bond prices may adjust
↓
Debt investment valuations can change
That does not mean every liquidity-absorption operation automatically causes every debt investment to decline.
The actual impact depends on the broader interest-rate environment and the securities held.
The Basic Relationship Between Bond Prices and Yields
This is one of the most important concepts for understanding debt investments.
Generally:
Bond prices and market yields move in opposite directions.
If market yields rise, existing bonds with lower fixed coupons can become less attractive relative to newly issued securities.
Their market prices may therefore decline.
If market yields fall, existing bonds with relatively higher coupons can become more valuable in the market.
Their prices may rise.
This relationship becomes particularly relevant for longer-duration securities because their prices tend to be more sensitive to changes in interest rates.
That is why simply saying:
“It is a debt investment, so the value should remain stable”
can be misleading.
Debt investments can experience price movements too.
How Can RBI Liquidity Absorption Influence This?
Suppose the banking system has a large amount of surplus liquidity.
The RBI may use its liquidity-management tools to absorb some of that excess.
The RBI has described liquidity management as an important part of maintaining orderly money-market conditions. Its operations can include absorption or injection depending on whether the system has surplus or deficit liquidity.
Now imagine that tighter liquidity contributes to upward pressure on short-term funding costs or market yields.
If market yields rise, existing bonds can experience price pressure.
For an investor holding a debt security or a debt-oriented mutual fund, this can show up through changes in market value or NAV, depending on the underlying portfolio.
This is why liquidity is not merely a banking-system concept.
It can eventually become relevant to debt-market investors.
Does a Liquidity Drain Automatically Mean Debt Mutual Funds Will Fall?
No.
This is an important distinction.
A debt mutual fund does not simply respond to one RBI liquidity operation in isolation.
Its valuation can be influenced by several factors, including:
- Interest-rate movements
- Maturity of the securities held
- Credit quality
- Changes in market yields
- Liquidity conditions
- Changes in spreads
- Portfolio composition
- Market expectations
The RBI has highlighted that debt mutual funds are exposed to liquidity considerations and that movements in debt-market conditions can affect the valuation of debt-oriented schemes.
Therefore, a liquidity drain is better understood as one factor within a larger chain of market forces, rather than a standalone signal about what every debt investment will do.
Short-Term vs Long-Term Debt: Why Maturity Matters
Consider two bonds.
Bond A
Matures relatively soon.
Bond B
Matures many years later.
If market yields suddenly change, their prices may not respond to the same extent.
Generally, securities with longer durations have greater sensitivity to interest-rate movements.
This means that the same change in market yields can have different valuation effects across different debt securities.
The RBI’s investor guidance also notes that government securities carry market risk and that changes in interest rates can create valuation losses when securities are sold at adverse prices.
So when thinking about debt investments, the question should not simply be:
“Is this debt?”
It can also be:
“What kind of debt is this, and how sensitive is it to changes in market yields?”
A Simple Example
Suppose a bond was issued when market yields were relatively low.
Later, market yields rise.
New bonds may now be issued with higher yields.
An existing bond with a lower fixed coupon may become less attractive in the secondary market.
To make its effective yield more competitive, its market price may need to adjust downward.
For an investor who continues holding the bond until maturity, the experience can be different from someone who sells it in the market before maturity.
This is one reason the RBI explains that holding eligible government securities until maturity can help an investor avoid market-price fluctuations associated with selling before maturity, although other risks—including reinvestment and liquidity risk—still exist.
The Bigger Lesson: Debt Does Not Mean “No Volatility”
The word “debt” can sometimes create a false sense of certainty.
Debt investments can have different forms of risk.
Depending on the instrument, these may include:
- Interest-rate risk
- Credit risk
- Liquidity risk
- Reinvestment risk
- Market-value fluctuations
The RBI’s material on government securities explicitly discusses market, reinvestment and liquidity risks.
Therefore, understanding a debt investment requires more than simply knowing that it belongs to the debt category.
You also need to understand what is inside it and how those securities may respond to changing financial conditions.
10. Practical Examples
Example 1: Why a Longer-Maturity Bond Can React More
Imagine a bond that has several years remaining until maturity.
Now suppose market interest rates move upward after you bought it.
A newly issued bond may offer a higher yield than the older bond. To make the older bond competitive in the market, its price may need to adjust downward.
This is the basic interest-rate risk mechanism.
The longer the maturity or duration, generally, the greater the sensitivity to changes in market yields. This is why two debt investments can respond differently to the same market event.
For example:
| Debt Investment Characteristic | General Interest-Rate Sensitivity |
| Very short maturity | Relatively lower |
| Short maturity | Lower than long-duration instruments |
| Medium maturity | Moderate |
| Long maturity | Higher |
This does not mean that every long-duration investment will fall whenever liquidity is drained. Market yields are influenced by several factors, including inflation expectations, monetary policy, government borrowing, credit conditions and investor demand.
The key lesson is that maturity and duration matter when understanding debt-market volatility.
Example 2: What Happens Inside a Debt Mutual Fund?
Suppose a debt mutual fund holds bonds whose market prices change.
The fund’s portfolio is generally valued using prevailing market valuations. Therefore, changes in the value of the underlying securities can affect the fund’s NAV.
If market yields rise, some existing bonds may decline in market value. That can create temporary downward pressure on the NAV of a debt-oriented mutual fund.
The reverse can also happen.
If market yields decline, existing bonds with comparatively higher coupons may become more valuable in the market, potentially supporting their market value.
This is one reason why debt mutual funds should not automatically be equated with fixed-value products.
RBI has also highlighted liquidity risks in debt mutual funds, particularly where investors can redeem frequently while some underlying securities may become less liquid during periods of market stress.
Example 3: Short-Term Debt and Long-Term Debt May Behave Differently
Consider two hypothetical portfolios.
Portfolio A primarily contains very short-term instruments.
Portfolio B contains bonds with considerably longer maturities.
If market yields suddenly move upward, Portfolio B may experience greater mark-to-market sensitivity because its securities have greater exposure to changes in interest rates.
Meanwhile, the shorter-term portfolio may have lower sensitivity because its securities mature and reprice more quickly.
However, shorter maturity does not mean zero risk.
Credit risk, liquidity risk and reinvestment risk can still exist.
So when someone says:
“It is debt, so the value should not fluctuate.”
that statement misses an important part of how debt markets actually work.
11. Liquidity Risk Is Different From Interest-Rate Risk
These two concepts are often mixed together.
Interest-rate risk
This relates to changes in the market value of a debt security when market interest rates or yields change.
Liquidity risk
This relates to how easily a security can be bought or sold without causing a significant price impact.
A security can therefore face a situation where:
- its market value changes because yields move, and
- selling becomes more difficult because market liquidity has weakened.
RBI’s discussion of government securities specifically identifies market risk, liquidity risk and reinvestment risk as different risks associated with debt instruments.
This distinction becomes particularly important during periods of market stress.
12. Does RBI Liquidity Drain Mean Debt Investments Will Fall?
Not automatically.
This is perhaps the most important point in the entire discussion.
RBI’s liquidity operations are designed to influence money-market liquidity and keep short-term market rates aligned with the monetary-policy framework. RBI can use different tools to absorb or inject liquidity depending on prevailing conditions.
But debt-market prices don’t respond to one variable alone.
For example, suppose liquidity is being absorbed while investors simultaneously expect lower inflation or lower future interest rates.
Different forces can then work in different directions.
Similarly, a liquidity drain can affect short-term money-market conditions without producing the same magnitude of movement across every maturity segment of the bond market.
Therefore, a better way to think about the relationship is:
RBI liquidity operation → money-market conditions → market interest rates/yields → bond valuations → possible impact on debt investment values
It is a transmission mechanism, not a simple one-step rule.
13. Common Misconceptions
Misconception 1: “RBI drains liquidity, so all debt investments must fall.”
Not necessarily.
The impact depends on the type of instrument, maturity, duration, prevailing yields, credit conditions, liquidity and market expectations.
Misconception 2: “Debt means there can be no loss.”
Debt instruments can experience market-value fluctuations.
RBI’s own investor information distinguishes market risk, liquidity risk and reinvestment risk in government securities.
The fact that an instrument represents a borrowing obligation does not eliminate all investment risks.
Misconception 3: “RBI liquidity operations are the same thing as a repo-rate change.”
They are related to monetary-policy implementation, but they are not identical concepts.
Liquidity management involves operations designed to influence system liquidity and short-term interest rates. RBI has described tools including repo/reverse-repo operations and open-market operations as part of its liquidity-management framework.
A change in the policy rate and an individual liquidity operation should therefore not automatically be treated as the same event.
Misconception 4: “All debt mutual funds respond in the same way.”
They don’t necessarily.
Two funds can have different:
- maturities,
- durations,
- credit profiles,
- liquidity profiles,
- portfolio compositions, and
- exposure to different segments of the debt market.
Consequently, the same market event can affect them differently.
Misconception 5: “Holding a bond until maturity removes every risk.”
Holding an eligible government security until maturity can reduce or avoid the market-price risk associated with selling before maturity, but it does not eliminate every possible risk. RBI also identifies reinvestment and liquidity considerations.
This is an important distinction between price volatility and overall investment risk.
14. Frequently Asked Questions
1. What does RBI liquidity drain mean?
It generally refers to RBI operations that absorb excess liquidity from the financial system. Such operations form part of RBI’s liquidity-management framework and can influence short-term money-market conditions.
2. Why can bond prices fall when yields rise?
Existing bonds have previously determined cash flows. When newly available market yields become higher, existing lower-yielding bonds may become less attractive. Their market prices can therefore adjust downward so that their effective yield becomes more competitive.
This is the basic inverse relationship between bond prices and yields.
3. Why are long-duration debt investments generally more sensitive?
Because their cash flows extend further into the future. Changes in discount rates can therefore have a larger effect on their present market value.
This is why duration is an important concept when studying interest-rate sensitivity.
4. Can debt mutual fund NAVs fluctuate because of RBI liquidity operations?
Yes, indirectly.
Liquidity conditions can influence market interest rates and yields, which can affect the market value of securities held by a debt mutual fund. Changes in those underlying valuations can consequently affect NAV.
The actual impact depends on the fund’s portfolio and prevailing market conditions.
5. Does a liquidity drain always mean interest rates will rise?
Not as a universal rule.
RBI’s liquidity operations interact with broader monetary and financial-market conditions. Market rates are also affected by factors such as demand and supply of funds, expectations, inflation and other market developments.
6. Are short-term debt instruments completely protected from liquidity changes?
No.
Shorter maturity generally means lower sensitivity to interest-rate changes than longer-duration instruments, but it does not remove credit, liquidity or reinvestment risks.
7. Why should investors understand duration?
Because duration provides a way to understand how sensitive a debt investment may be to changes in interest rates.
It can therefore help explain why two debt investments with apparently similar objectives may show different levels of market-value movement.
15. Key Takeaways
If you remember only a few points from this article, remember these:
- RBI liquidity management affects financial-market conditions, particularly short-term liquidity and money-market rates.
- Liquidity changes can influence interest rates and market yields.
- Bond prices and yields generally move in opposite directions.
- Longer-duration debt instruments are generally more sensitive to changes in market yields.
- Debt investments can experience market-value fluctuations even though they are not equity investments.
- Debt mutual fund NAVs can be affected by changes in the market value of their underlying securities.
- Interest-rate risk and liquidity risk are different risks.
- RBI liquidity operations do not mean that every debt investment will move in exactly the same direction or by the same magnitude.
- Holding a security until maturity can address certain market-price concerns, but it does not eliminate every form of risk.
- Understanding liquidity, yields, duration and valuation makes debt-market movements easier to interpret.
16. Conclusion
When people hear that “RBI is draining liquidity,” it can sound like a technical banking announcement with little relevance to an ordinary investor.
But the connection can eventually reach debt investments.
Liquidity conditions can influence short-term funding markets. Market rates and yields can respond. Bond prices can then adjust, and those changes can flow through to the market value of debt securities and, where applicable, the NAV of debt mutual funds.
But the process is not automatic or identical for every investment.
The maturity and duration of the underlying securities matter. So do credit quality, liquidity, market expectations and broader economic conditions.
The bigger lesson is this:
Debt investments are not simply about earning interest. They also involve understanding how interest rates, bond prices, liquidity and time interact.
Once this framework becomes clear, movements in debt investment values become much easier to understand.
If you found this article helpful, explore more Financial Awareness and Investor Education articles on Finoniq Wealth to build a clearer understanding of how financial markets work.